Implementing Multi-Layered Validation for MICR Line Integrity
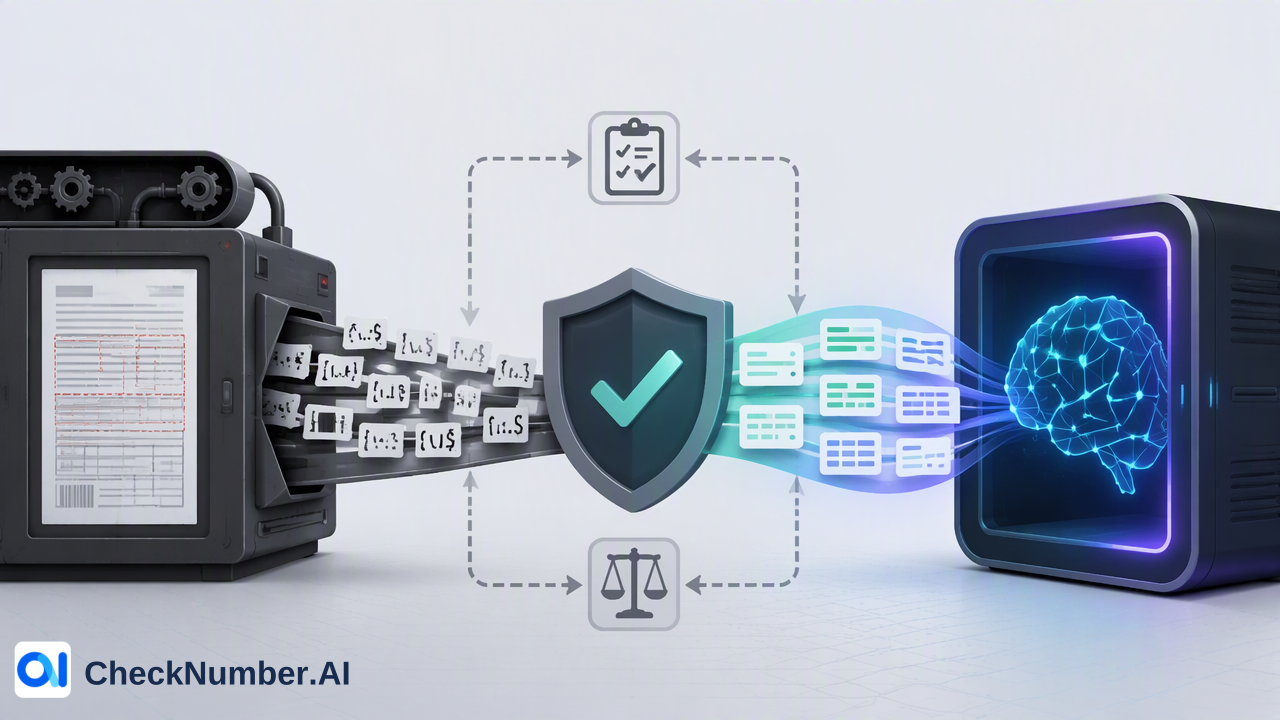
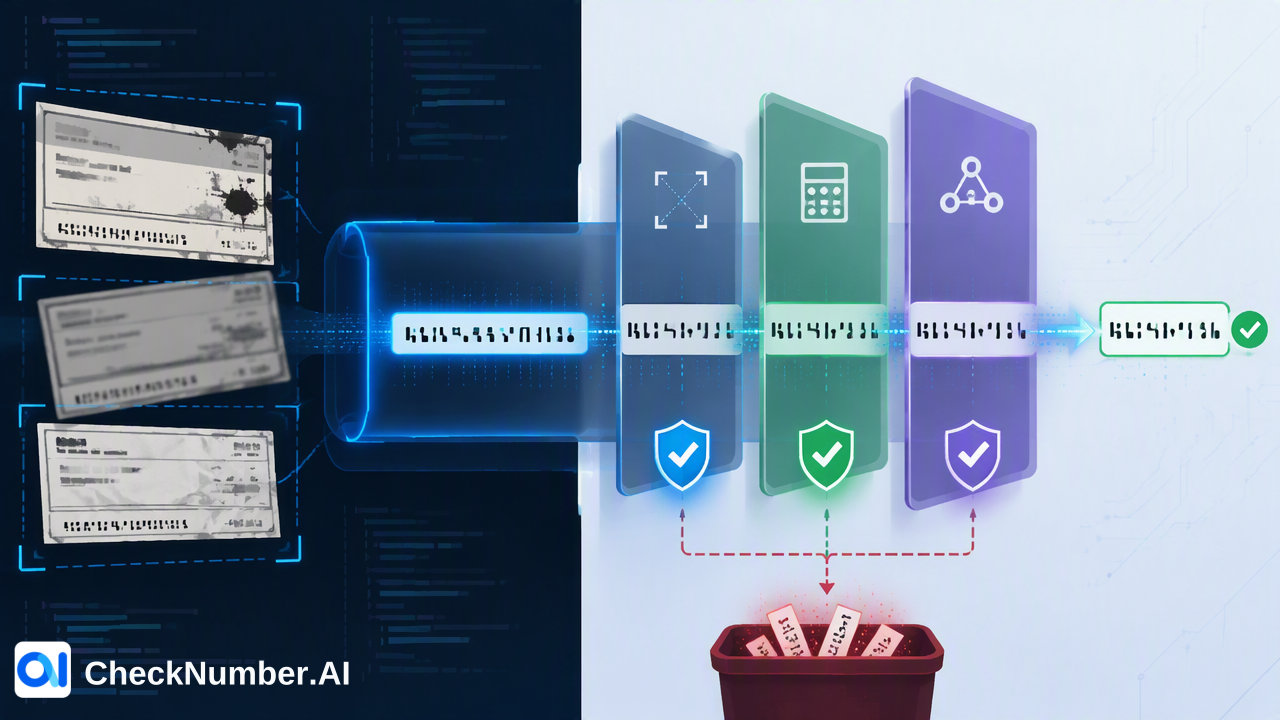
Relying solely on OCR confidence scores for financial document processing is insufficient; developers must implement a multi-layered validation strategy that combines geometric verification, checksum algorithms, and cross-field reconciliation to ensure data integrity.
The Illusion of OCR Confidence
In financial document processing, the Magnetic Ink Character Recognition (MICR) line—the string of numbers at the bottom of a check—is the primary source of truth for routing and account identification. When building an ingestion pipeline, it is tempting to rely on the confidence scores returned by Optical Character Recognition (OCR) engines. If the engine reports a 98% confidence score, the assumption is that the data is accurate.
However, this assumption often leads to silent data corruption. I recently encountered a scenario where a batch of checks was processed with high confidence scores, yet the downstream ledger reconciliation failed. Upon investigation, I discovered that the OCR engine had misidentified a "0" as a "D" or a "5" as an "S" due to ink bleed on the paper. Because these characters were geometrically similar to the OCR's training set, the engine assigned them high confidence, even though they were syntactically invalid for a MICR line.
Relying solely on OCR confidence is a dangerous architectural pattern. To build a robust pipeline, you must treat OCR output as a "suggestion" rather than a "fact."
Layer 1: Structural Pattern Matching
The first line of defense is structural validation. A standard MICR line follows a rigid format defined by industry standards (such as ANSI X9.27). It consists of three primary fields: the Transit Routing Number (TRN), the On-Us field (account number), and the Auxiliary On-Us field (check number).
These fields are delimited by specific symbols: the transit symbol (⑆), the on-us symbol (⑇), the amount symbol (⑈), and the dash symbol (⑉).
Before performing any complex logic, your pipeline should use a regex-based validator to ensure the string conforms to the expected structure. If the OCR returns a string that lacks these delimiters or contains invalid characters (like letters where only digits should exist), the record should be rejected immediately.
import re

def validate_micr_structure(micr_line):
    # Standard MICR pattern: ⑆TRN⑆ Account ⑇
    # Symbols are often represented as A, B, C, D in OCR output
    # Regex checks for presence of required delimiters and numeric segments
    pattern = r"A\d{9}A\d+C"
    if not re.match(pattern, micr_line):
        return False
    return True
Layer 2: Checksum Verification
Even if the structure looks correct, the digits themselves might be wrong. Most MICR fields, particularly the Transit Routing Number, include a built-in checksum. The routing number uses a weighted modulus-10 algorithm.
If the OCR misreads a single digit, the checksum calculation will fail. This is your most powerful tool for catching "high confidence" errors. If the OCR says the routing number is 123456789 but the checksum calculation returns a mismatch, you know the OCR is wrong, regardless of what the confidence score says.
def validate_routing_checksum(routing_number):
    # Weights for the routing number checksum: 3, 7, 1, 3, 7, 1, 3, 7
    weights = [3, 7, 1, 3, 7, 1, 3, 7]
    digits = [int(d) for d in routing_number[:8]]
    check_digit = int(routing_number[8])

    total = sum(d * w for d, w in zip(digits, weights))
    remainder = total % 10
    calculated_check = (10 - remainder) % 10

    return calculated_check == check_digit
Layer 3: Cross-Field Reconciliation
The final layer involves cross-field reconciliation. In many financial systems, the MICR line is not the only source of data. You likely have a document header, a user-provided input field, or a database record associated with the transaction.
If the OCR-extracted routing number points to a bank that does not exist or is inconsistent with the bank name printed elsewhere on the document, you have a conflict. A robust pipeline should flag these discrepancies for manual review rather than attempting to "fix" them programmatically.
Handling Edge Cases and Trade-offs
One common edge case is the "non-standard font." Some financial institutions use proprietary fonts that confuse standard OCR models. In these cases, the OCR might consistently misread a specific character.
A trade-off you must accept is the balance between False Rejections and False Acceptances.
- Strict Validation: You reject more documents, requiring more manual intervention, but you ensure high data integrity.
- Loose Validation: You accept more documents, but you increase the risk of downstream ledger errors that are significantly more expensive to fix.
In a financial context, the cost of a manual review is almost always lower than the cost of a misrouted payment. Therefore, err on the side of strictness.
Implementation Strategy
When building this into your pipeline, follow this sequence:
- Sanitization: Convert OCR-specific character mappings (e.g., mapping 'A' to '⑆') to a standard internal representation.
- Structural Check: Reject if the regex pattern does not match.
- Checksum Validation: Reject if the modulus-10 calculation fails.
- Contextual Reconciliation: Compare the extracted data against your internal database of known routing numbers.
- Confidence Thresholding: Only use the OCR confidence score as a tie-breaker for manual review, never as a primary validation signal.
Key Takeaways
- Confidence is not Accuracy: High OCR confidence scores often mask systematic errors caused by font variations or image artifacts.
- Checksums are Mandatory: Always implement the modulus-based checksum validation for routing numbers. It is the only way to mathematically verify the integrity of the digits.
- Fail Fast: If a MICR line fails structural or checksum validation, reject it before it touches your database.
- Prioritize Integrity: In financial systems, a false rejection is a minor operational inconvenience; a false acceptance is a significant financial risk.
- Use Multiple Signals: Combine geometric verification, checksum algorithms, and cross-field reconciliation to create a defense-in-depth strategy for document ingestion.